
How to Prepare Your Finances Before Divorce
Divorce can change almost every part of your financial life.
Housing, bank accounts, credit cards, insurance, retirement savings, monthly expenses, and debt may all become part of the larger conversation. When you are already dealing with the emotional side of ending a marriage, trying to understand the financial side at the same time can feel overwhelming.
That is why financial preparation before divorce does not begin with trying to predict who will get what.
It begins with understanding where you stand today.
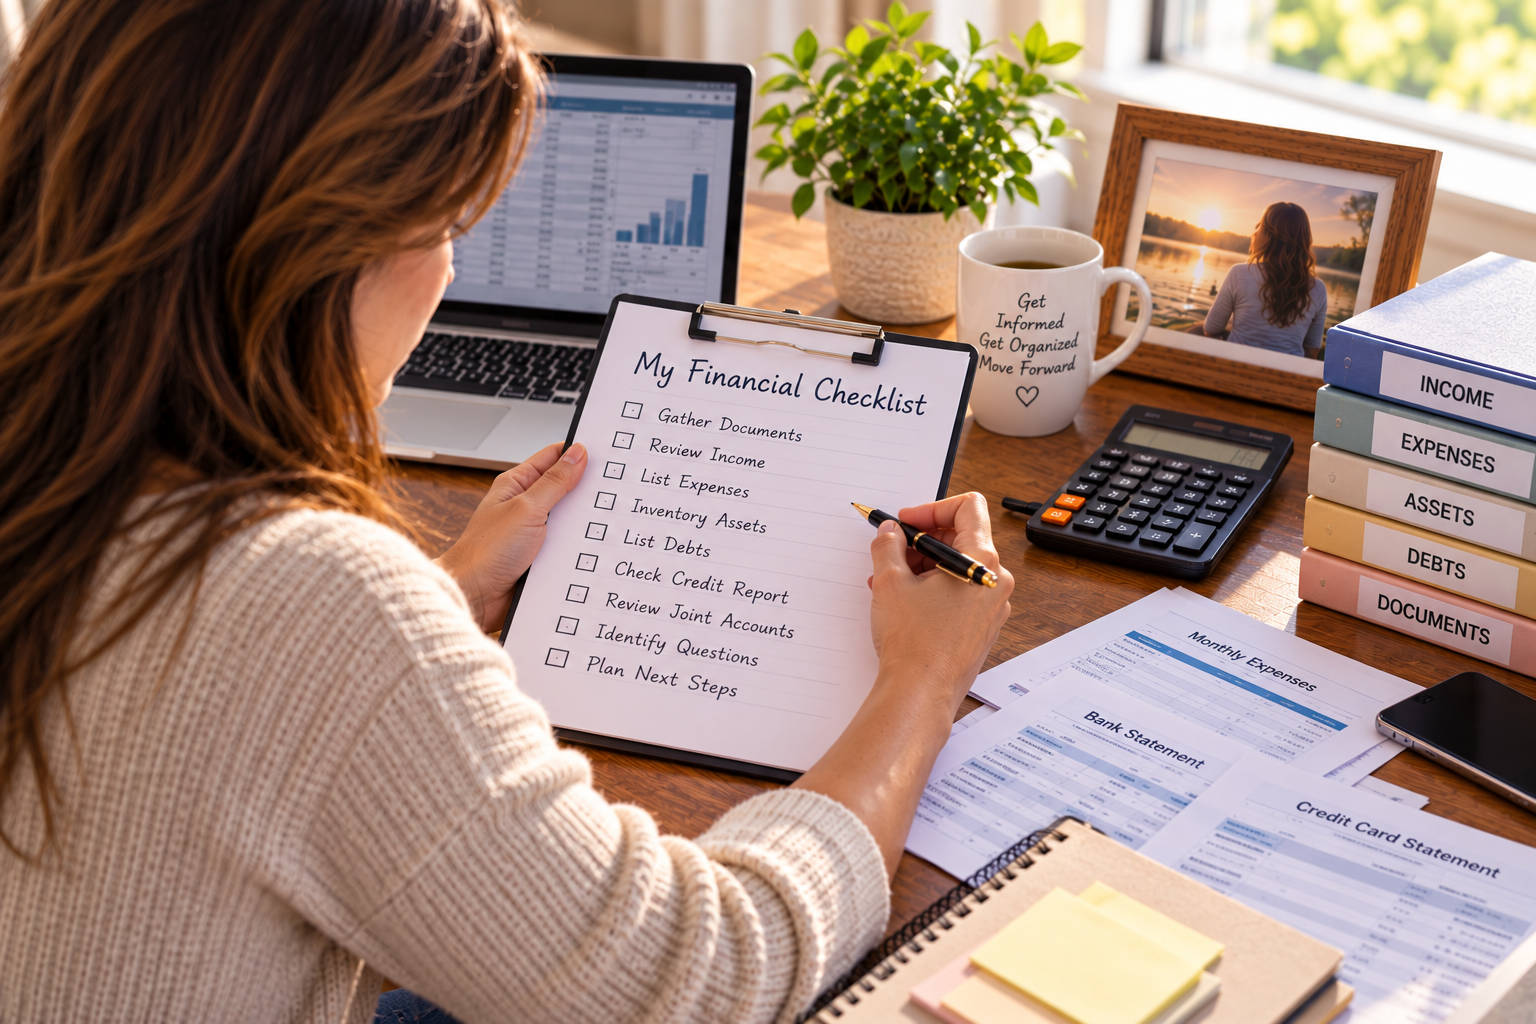
Before making major decisions, get informed, get organized, and build a clear picture of the financial life you currently have.
1. Gather Your Financial Documents
One of the most useful things you can do when financially preparing for divorce is gather the records you are legally authorized to access.
Depending on your circumstances, these may include:
Recent tax returns
Pay stubs and other income records
Bank statements
Credit card statements
Mortgage and loan documents
Investment account statements
Retirement account statements
Insurance policies
Records relating to significant property
Relevant business financial records
You do not need to understand every document immediately.
The first goal is simply to know what exists and keep your records organized. Missing information can become much easier to identify once everything you already have is in one place.
2. Understand Your Income and Monthly Expenses
Next, look at the money coming into the household and where it is going.
Start with your regular monthly expenses: housing, utilities, groceries, transportation, insurance, healthcare, childcare, debt payments, subscriptions, and other recurring costs.
Do not rely entirely on estimates if you have access to actual statements and bills.
This exercise is not about creating a perfect post divorce budget yet. It is about understanding what your current life actually costs.
That information gives you a more realistic starting point for thinking about what may change later.
3. Make an Inventory of Your Assets
JCreate a list of the major assets you know about.
That may include your home or other real estate, checking and savings accounts, investments, retirement accounts, vehicles, business interests, and other significant property.
For each item, note what you know: where it is held, whose name appears on it, and what documentation you have.
At this stage, avoid assuming that having one person's name on an asset automatically determines how it will be treated in a divorce. Property rules vary by jurisdiction and individual circumstances.
The purpose of the inventory is clarity.
4. Make a Complete List of Your Debts
Assets are only half of the financial picture.
List mortgages, credit cards, car loans, personal loans, student loans, medical bills, and other outstanding obligations.
Pay particular attention to whose names appear on each account and whether an obligation is individual or joint.
This matters because a divorce agreement and your obligations to a creditor are not necessarily the same thing. Understanding exactly what you owe and where your name appears can help you ask better questions before making financial decisions.
For a deeper explanation of this issue, our related guide, What Happens to Debt When You Get Divorced?, walks through divorce and debt in more detail.
5. Review Your Joint Financial Connections
Divorce does not instantly untangle every financial connection between two people.
Make a list of joint checking and savings accounts, joint credit cards, mortgages, co signed loans, shared insurance policies, and other accounts that connect you financially.
The important word here is identify.
Do not assume that you should immediately withdraw money, transfer assets, close accounts, or change ownership. Those decisions can have financial and legal consequences depending on the circumstances.
First understand what exists. Then get appropriate professional advice about what should happen next.
6. Review Your Credit
Your credit reports can provide another view of accounts associated with your name.
Review them for accounts you recognize, balances that need your attention, and information that appears inaccurate or unfamiliar.
A credit report should not be treated as a complete inventory of every financial obligation you have, but it can be a useful cross check against the records you have already gathered.
If something surprises you, write it down and investigate rather than ignoring it.
7. Build a Realistic Picture of Life After Divorce
You may not know exactly what your finances will look like after divorce, and you do not need to pretend that you do.
Instead, start building reasonable scenarios.
What might housing cost? What expenses would you be responsible for independently? How could insurance, transportation, childcare, food, utilities, and ordinary living expenses change?
The goal is not to predict the outcome of your divorce.
It is to understand what questions you need answered and what financial realities you may need to prepare for.
8. Identify What You Don't Know
One of the most valuable parts of financial preparation is discovering the gaps in your knowledge.
Maybe you do not understand a retirement account. Perhaps you are unsure whose name is on a particular debt. Maybe you do not know the current mortgage balance or understand the tax consequences of a potential decision.
Write those questions down.
A good financial checklist should not simply tell you what you know. It should reveal what you still need to learn.
9. Know When to Get Professional Guidance
Some questions cannot responsibly be answered by a general article.
Divorce laws and property rules vary by jurisdiction, and tax and financial consequences can depend heavily on individual circumstances.
A qualified attorney can help you understand the legal issues that apply to your situation. A qualified tax or financial professional may also be appropriate when decisions involve taxes, investments, retirement assets, or longer term financial planning.
The more organized you are before those conversations, the easier it may be to focus on the questions that actually matter.
Financial Preparation Is About Clarity
Preparing your finances before divorce is not about solving every problem before the process begins.
It is about replacing uncertainty with information.
Know what you earn.
Know what you spend.
Know what you own.
Know what you owe.
Know where you are still financially connected.
And know what you still need to ask.
Get informed. Get organized. Understand the numbers in front of you.
Then make the next decision from a clearer position.
Legal Disclaimer
This article is provided for general informational and educational purposes only and is not legal, financial, tax, or other professional advice. Divorce, property, and financial laws vary by jurisdiction, and the appropriate course of action depends on the specific facts and circumstances of each situation. Nothing in this article creates an attorney client relationship or guarantees any particular outcome. Before making decisions concerning divorce, property, debt, finances, or other legal matters, consult with a qualified attorney licensed in your jurisdiction and, where appropriate, a qualified financial or tax professional who can evaluate your individual circumstances.
A Practical Next Step
Preparing financially for divorce does not mean you need to have every answer today.
Start by understanding what you earn, what you spend, what you own, what you owe, and where you are still financially connected.
If you are looking for a practical place to begin organizing the larger rebuilding process, The Reconstruction Toolkit can help you start working through the areas that may need your attention.
Get the Free Reconstruction Toolkit
If you want to go deeper into the divorce process, The Divorce Reconstruction: A Practical Guide to Surviving, Rebuilding, and Thriving After Your Marriage Ends expands the discussion beyond financial preparation into family concerns, legal issues, and rebuilding afterward.
Explore The Divorce Reconstruction
If divorce is affecting several areas of your life at once, The Reconstruction System™ Master Edition brings the broader framework together across Law, Money, Body, and Identity.
Explore the Reconstruction System™ Master Edition
You do not need to solve every financial question today.
Get informed. Get organized. Understand the numbers in front of you.
Then make the next decision from a clearer position.
Keep Rebuilding
Not ready for a book or the full system? David Reinherz on Substack for practical writing on divorce, money, rebuilding, and life after major disruption.
